


By Elizabeth Costa | Top Real Estate Agent in Doral & Miami | The Keyes Company
15+ years of experience · 300+ closed transactions · Bilingual: English & Spanish
Exclusive Member of Forbes Global Properties · Founding Member of Luxury Portfolio International
★ 5.0 · 83 Google reviews
Last updated: November 20, 2026, with Miami MLS data through October 30, 2026
What happens if the appraisal comes in low in Miami-Dade?
A low appraisal does not cancel a Florida sale by itself. Under the standard FR/BAR contract, the buyer can cancel only if the lender will not approve the loan in time, or if an appraisal addendum or the FHA or VA clause applies. Otherwise, buyer and seller renegotiate, split the gap, or challenge the appraisal.
Key Takeaways
- Under the FR/BAR Residential Contract, loan approval includes an appraisal satisfactory to the lender; if the lender still approves the loan after a low appraisal, the buyer generally has no right to cancel (Florida Realtors Legal Hotline).
- A specific appraisal contingency is optional: it is added with Addendum F, and FHA and VA purchases carry a federal clause that lets the buyer walk away with the deposit if the value comes in below a set amount (Florida Realtors, HUD).
- For a conventional purchase, Fannie Mae measures the loan against the lower of the sales price or the appraised value, so the buyer's cash has to cover any gap (Fannie Mae Selling Guide B2-1.2-01).
- In Doral, only 7 of 174 home sales from August 4 to October 30, 2026, closed above the list price, and 86% closed below it, while 70% of buyers used a loan (Miami MLS).
- Lenders must give the buyer a copy of the appraisal promptly upon completion or three business days before closing, whichever is earlier (12 CFR 1002.14).
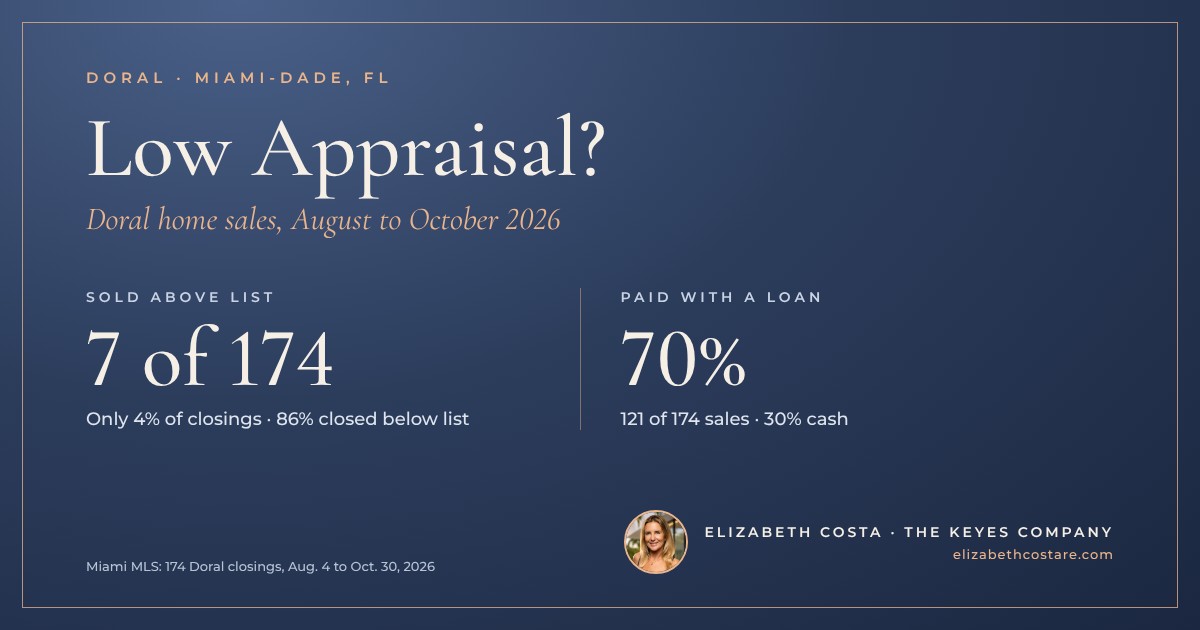
Doral home sales above list price and share of financed purchases, Miami MLS, August to October 2026.
Does a Low Appraisal Cancel the Contract in Florida?
Not by itself. In the FR/BAR Residential Contract for Sale and Purchase, the most common contract in Miami-Dade, the financing contingency in paragraph 8(b) covers two things: approval of the loan and "an appraisal or alternative valuation of the Property satisfactory to lender." The buyer has a Loan Approval Period, 30 days after the effective date if left blank, to get both. As the Florida Realtors Legal Hotline explains, if the lender gets a low appraisal but still approves the loan, the buyer has no right to cancel under that paragraph. If the lender will not approve the loan, the buyer can cancel by written notice before the period ends and get the deposit back.
Timing matters. If the buyer sends no written notice before the Loan Approval Period expires, the contract continues as if it were a cash deal, and the seller has three days to cancel. Paragraph 9 makes appraisal fees a buyer cost.
What Are Addendum F and the FHA and VA Appraisal Clause?
- Addendum F, Appraisal Contingency: an optional addendum to the FR/BAR contract. The buyer can get an appraisal by a negotiated deadline and, if the value comes in below the amount written in the addendum, cancel without penalty or proceed to closing (Florida Realtors).
- FHA and VA purchases: HUD's amendatory clause says the buyer is not obligated to complete the purchase or forfeit the deposit unless the appraised value is at least the amount stated, and keeps the option to proceed anyway. Florida Realtors notes that the FHA and VA provisions override other contract terms.
How Much Extra Cash Does a Low Appraisal Cost the Buyer?
For a conventional purchase, Fannie Mae defines the property value for the loan-to-value ratio as "the lower of the sales price or the current appraised value." So if the appraisal is low and the price stays the same, the buyer's cash has to cover the difference. A hypothetical townhouse example near the Doral townhouse median:
| Hypothetical example | Appraisal at price | Appraisal $20,000 low |
|---|---|---|
| Purchase price | $650,000 | $650,000 |
| Appraised value | $650,000 | $630,000 |
| Value the lender uses (lower of the two) | $650,000 | $630,000 |
| Loan at 80% | $520,000 | $504,000 |
| Cash the buyer brings (before closing costs) | $130,000 | $146,000 |
| Extra cash needed | $16,000 |
Hypothetical example for illustration, not a loan quote. Loan limits, mortgage insurance, and down payment rules vary by program; confirm with a lender of your choice.
What Are the Options When the Appraisal Comes In Low?
| Option | Who gives | When it fits |
|---|---|---|
| Seller lowers the price to the appraised value | Seller | Several recent sales support the lower value |
| Buyer pays the difference in cash | Buyer | The buyer has the cash and wants this home |
| Split the difference | Both | Both sides want to keep the deal |
| Ask the lender for a reconsideration of value | Buyer, through the lender | The appraisal has errors or missed closer sales |
| Cancel, if the contract allows it | Buyer | No loan approval in time, Addendum F, or the FHA or VA clause applies |
The CFPB notes that buyers can often use a lower appraised value to negotiate the price, and that cancelling may have costs depending on the contract. A buyer who believes the appraisal is wrong can ask the lender for a reconsideration of value, for example because of factual errors or inadequate comparable sales.
Elizabeth's Take
When an appraisal comes in low, my first call is not to the other agent; it is to the buyer's lender, to read the appraisal and check its comparable sales. If it missed a closer or newer sale, that becomes the reconsideration request. Only then do we talk price, and we talk with the numbers on the table, not with emotions.
In This Guide
How Often Do Doral Homes Sell Above the List Price?
Rarely in 2026. An appraisal gap is most likely when a financed buyer pays more than recent sales support, which usually means paying over list in a competitive situation. In Doral, that was the exception:
| Sale price vs. last list price | Sales | Share |
|---|---|---|
| Above list | 7 | 4% |
| At list | 18 | 10% |
| Below list | 149 | 86% |
| Median sale-to-list ratio | 96.8% |
Most buyers depend on a loan, and therefore on an appraisal:
| Doral home sales, Aug. 4 to Oct. 30, 2026 | Sales | Share |
|---|---|---|
| Conventional loan | 99 | 57% |
| Cash | 53 | 30% |
| FHA or VA loan | 11 | 6% |
| Other financing (non-QM, private, other) | 11 | 6% |
| Total | 174 | 100% |
Of the 121 financed purchases, only 6 closed above list, and 4 of them were townhouses:
| Financed sales (loan), by property type | Financed sales | Closed above list |
|---|---|---|
| Condo | 42 | 1 |
| Townhouse | 41 | 4 |
| Single-family | 38 | 1 |
| Total financed | 121 | 6 |
Source: Miami MLS, 174 Doral closings (single-family, townhouse, and condo; ZIPs 33178, 33166, 33172, and 33122), August 4 to October 30, 2026. The MLS does not record appraised values, so these figures show where appraisal risk is higher, not how many appraisals came in low. See the Doral townhomes for sale and Doral homes for sale pages for live listings.
Can I Get a Copy of the Appraisal?
Yes. Under 12 CFR 1002.14, the lender must give the applicant a copy of each appraisal promptly upon completion or three business days before closing, whichever is earlier, and must send a notice of this right within three business days of a first-lien mortgage application. The buyer can waive the timing, but the waiver must be given at least three business days before closing.
What Can Sellers Do About a Low Appraisal?
Sellers cannot order the buyer's appraisal, but they can prepare. Price with recent closed sales in the same community, not only active listings. Give the buyer's agent a list of recent comparable sales and improvements with dates and permits, so it can reach the appraiser through the lender's process. When reviewing offers, compare the loan type, the down payment, and whether the offer includes Addendum F or the FHA or VA clause, not only the price. For more on the timeline, see What Happens After I Accept an Offer in Florida?
What to Do When the Appraisal Comes In Low: Step by Step
- Get the appraisal. Ask the lender for the full report. Lenders must provide it promptly upon completion or three business days before closing, whichever is earlier.
- Check your deadlines. Find the Loan Approval Period in paragraph 8 of the contract (30 days if left blank) and any Addendum F deadline. Written notice must go out before they expire.
- Review the comparable sales. Compare the appraiser's sales with recent sales in the same community, same size, and same condition.
- Request a reconsideration of value if warranted. If there are factual errors or better comparable sales, the buyer asks the lender for a reconsideration of value.
- Run the numbers. Calculate the extra cash the buyer needs at the lender's loan-to-value limit, and what each side can give.
- Negotiate in writing. Price reduction, buyer covering the gap, or a split. Any change goes in a written amendment to the contract.
- Cancel only if the contract allows it. If the lender will not approve the loan in time, or Addendum F or the FHA or VA clause applies, the buyer sends written notice and the deposit is returned.
Budget for buyer closing costs, and sellers can estimate theirs with How Much Does It Cost to Sell a Home in Doral?
Buying or selling in Doral? See how I work with clients: Selling in Doral and Miami, Real Estate Specialties.
Related Doral Research
- What Happens After I Accept an Offer in Florida?
- The Florida Buyer Agreement Explained
- Is My Home Equity Safe in Doral?
- Should I Sell My Doral Home Now or Wait for Spring?
- Doral Townhouse vs. Single-Family Home
Frequently Asked Questions
Sources
- Miami MLS: 174 Doral closings (single-family, townhouse, condo; ZIPs 33178, 33166, 33172, 33122), August 4 to October 30, 2026 (Elizabeth Costa, The Keyes Company)
- Florida Realtors / The Florida Bar, Residential Contract for Sale and Purchase 7x (2026 redline), paragraphs 8 and 9
- Florida Realtors Legal Hotline, Financing Contingency FAQs (July 29, 2024)
- Florida Realtors, Analyzing the Financing Contingency (May 28, 2024)
- HUD, FHA Amendatory Clause model document (March 2023)
- Fannie Mae Selling Guide B2-1.2-01, Loan-to-Value (LTV) Ratios
- 12 CFR 1002.14, Rules on providing appraisals and other valuations
- CFPB, My appraisal is less than the sale price. What does that mean for me? (reviewed September 11, 2024)
- CFPB, Mortgage borrowers can challenge inaccurate appraisals through the reconsideration of value process
Worried About the Appraisal?
I review the comparable sales, the contract deadlines, and the numbers with you before anyone talks price. Bilingual EN/ES service.
Call or Text (786) 949-3971 |
Elizabeth Costa, Realtor | FL Lic. #3234205 ★ 5.0 · 83 Google reviews Top Real Estate Agent in Doral, Florida | The Keyes Company ☎ (786) 949-3971 ✉ elizabethcosta@keyes.com 📅 Schedule a private consultation 15+ years · 300+ closed transactions · Bilingual EN/ES Office: 4191 NW 107th Ave, Doral, FL 33178 Serving Doral, Miami, Coral Gables, Weston, Pinecrest, and surrounding South Florida communities The Keyes Company: Exclusive Member of Forbes Global Properties · Founding Member of Luxury Portfolio International |
This article is general real estate information, not legal, tax, or lending advice. Contract terms vary; read your own contract and consult a Florida real estate attorney and a lender of your choice. Figures are from Miami MLS samples and change over time.