


By Elizabeth Costa | Top Real Estate Agent in Doral & Miami | The Keyes Company
15+ years of experience · 300+ closed transactions · Bilingual: English & Spanish
Exclusive Member of Forbes Global Properties · Founding Member of Luxury Portfolio International
★ 5.0 · 83 Google reviews
Last updated: November 5, 2026
Should I sell my Doral home if I have a low mortgage rate?
Maybe. About half of U.S. mortgages carry a rate below 4%, while the 30-year rate averaged 7.24% in late October 2026. A low rate is worth real money, but so is your life rate: how well the home fits your space, costs, and plans. With a bigger down payment, the new rate may matter less than you think.
Key Takeaways
- 49.9% of outstanding U.S. mortgages had a rate below 4% in the first quarter of 2026, including 19.5% below 3% (FHFA National Mortgage Database).
- The 30-year fixed rate averaged 7.24% on October 29, 2026, up from 6.17% a year earlier (Freddie Mac).
- Hypothetical: a $400,000 loan costs $1,686 a month at 3% and $2,726 at 7.24%, but a $245,000 loan at 7.24% costs $1,670.
- The median Doral single-family home sold for $1,022,500 and the median townhouse for $645,000 in the last 12 months (Miami-Dade MLS).
- Homestead portability can transfer up to $500,000 of Save Our Homes savings to your next Florida homestead.
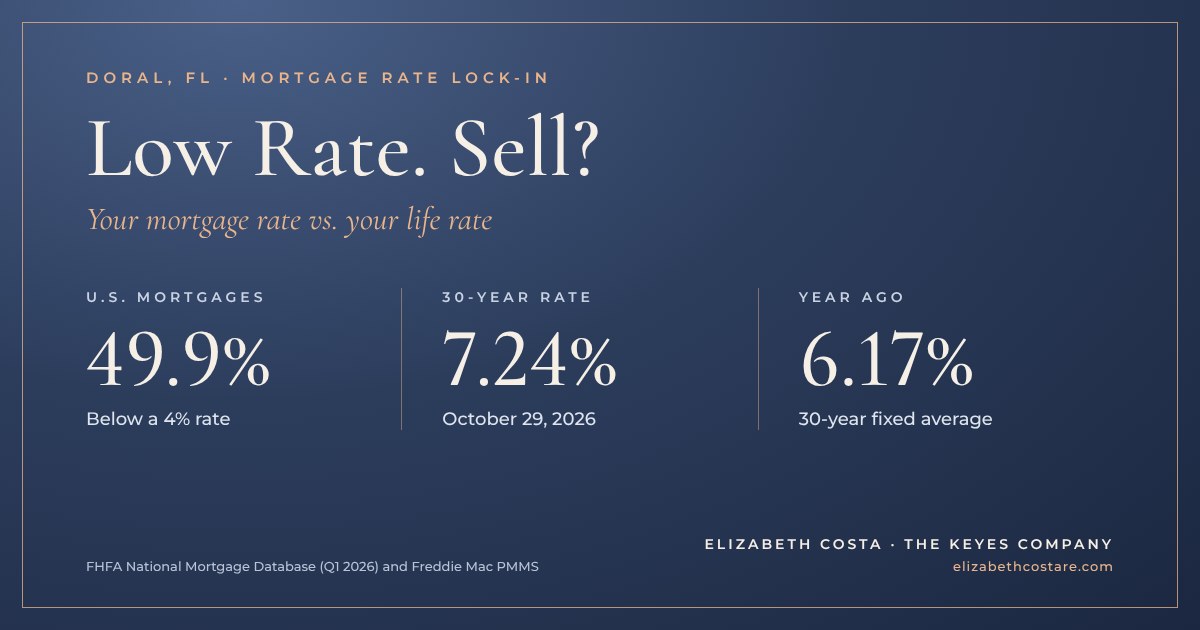
Mortgage rate lock-in by the numbers: FHFA National Mortgage Database and Freddie Mac, 2026.
How Many Homeowners Are Locked In by a Low Rate?
About half of U.S. homeowners with a mortgage. Here is how outstanding mortgages break down by rate:
| Rate on outstanding U.S. mortgages | Share of mortgages |
|---|---|
| Below 3% | 19.5% |
| 3% to 3.99% | 30.4% |
| 4% to 4.99% | 16.8% |
| 5% to 5.99% | 11.2% |
| 6% or higher | 22.1% |
| Below 4% combined | 49.9% |
Source: FHFA National Mortgage Database, first quarter of 2026, as reported by Wolf Street (July 1, 2026). Today's rate: Freddie Mac Primary Mortgage Market Survey, 7.24% for the 30-year fixed on October 29, 2026.
What Is a Life Rate, and How Does It Compare to a Mortgage Rate?
Your mortgage rate is fixed. Your life rate is how well your home fits the way you live today, and it changes. Ask yourself these five questions:
- Does the home still fit how you live? Rooms you no longer use still cost you in taxes, insurance, and cooling.
- How much of your time goes to upkeep? Yard, pool, roof, and exterior maintenance are part of what the home costs you.
- Are your other monthly costs rising? Property taxes, insurance, and HOA fees are not locked like your rate is.
- Does the location fit your daily routine? A shorter commute or being closer to what matters has value too. See my Doral commute guide.
- What could your equity do for you? Equity sitting in a house you have outgrown could become a larger down payment, a smaller loan, or a cushion.
Elizabeth's Take
A 3% rate is a great deal on a loan. It is a bad deal if it keeps you in a house that no longer fits your life. When clients tell me they feel stuck, we put two numbers on the table: what the rate saves you each month, and what staying costs you in space, upkeep, and time. Sometimes the rate wins. Often it is closer than people expect.
In This Guide
Does a Higher Rate Always Mean a Higher Payment?
Not if the loan is smaller. When you sell, your equity can go into the next home, so you may need to borrow less:
| Hypothetical scenario | Loan amount | Rate | Monthly principal and interest |
|---|---|---|---|
| Stay: current loan | $400,000 | 3.00% | $1,686 |
| Move with the same loan size at today's rate | $400,000 | 7.24% | $2,726 |
| Downsize and put $400,000 of equity down | $245,000 | 7.24% | $1,670 |
Hypothetical example for illustration only: 30-year fixed loans, principal and interest only. It does not include taxes, insurance, HOA, closing costs, or selling costs. Your rate and terms depend on the lender of your choice.
What Does This Mean for Doral Homeowners?
- Equity can be large. The median Doral single-family home sold for $1,022,500 in the last 12 months, and the median townhouse for $645,000. Moving from one to the other frees up equity for a larger down payment. See Is It Time to Downsize From Your Doral Home?
- Your tax savings can travel. With homestead portability, part of your Save Our Homes difference can move to your next Florida homestead.
- Waiting is not free. Taxes, insurance, and upkeep keep rising while you wait for rates. Weigh it with Should I Sell My Doral Home Now or Wait for Spring?
How to Decide Whether to Give Up a Low Rate: Step by Step
- Write down your current payment. Principal and interest, plus taxes, insurance, and HOA.
- Get a pricing analysis. Request a valuation based on recent sales in your community.
- Estimate your net equity. Sale price minus your payoff and selling costs.
- Price the next home. Townhouse, condo, or smaller single-family home in the community you want.
- Talk to a lender of your choice. Ask for payments at different down payments, without counting on a rate drop.
- Compare both scenarios. Monthly cost and life fit: staying vs. moving.
- Check portability. Estimate how much of your homestead savings could transfer to the new home.
Estimate your net with How Much Does It Cost to Sell a Home in Doral?, and plan both moves with Should I Sell My Doral Home Before I Buy?
Weighing a move? See how I work with sellers: Selling in Doral and Miami, Real Estate Specialties.
Related Doral Research
- Is It Time to Downsize From Your Doral Home?
- Should I Sell My Doral Home Now or Wait for Spring?
- Should I Sell My Doral Home Before I Buy?
- Florida Homestead Exemption and Portability
- How Much Does a Townhouse Cost in Doral?
- Seller's Guide
Frequently Asked Questions
Sources
- FHFA National Mortgage Database: Outstanding Residential Mortgage Statistics
- Wolf Street: Unwinding the Lock-in Effect (July 1, 2026)
- Freddie Mac: Mortgage Rates Decline Further to 7.24% (October 29, 2026)
- Freddie Mac Primary Mortgage Market Survey
- Miami-Dade MLS: 460 Doral single-family and townhouse closings, November 1, 2025 to October 27, 2026
- Miami-Dade Property Appraiser: Portability
Feel Stuck by Your Rate? Let's Run Both Numbers.
I will price your home, estimate your equity and portability, and compare staying with moving, side by side. Bilingual EN/ES service.
Call or Text (786) 949-3971 |
Elizabeth Costa, Realtor | FL Lic. #3234205 ★ 5.0 · 83 Google reviews Top Real Estate Agent in Doral, Florida | The Keyes Company ☎ (786) 949-3971 ✉ elizabethcosta@keyes.com 📅 Schedule a private consultation 15+ years · 300+ closed transactions · Bilingual EN/ES Office: 4191 NW 107th Ave, Doral, FL 33178 Serving Doral, Miami, Coral Gables, Weston, Pinecrest, and surrounding South Florida communities The Keyes Company: Exclusive Member of Forbes Global Properties · Founding Member of Luxury Portfolio International |
This article is general real estate information, not lending, tax, or financial advice. Payment examples are hypothetical. Talk to the lender of your choice about your options.